bKash, Robi Among Four Entities Receive Initial Approval For Digital Banks In Bangladesh
Bangladesh Bank board grants initial approval to four digital banks: Digital Banking of Bhutan, bKash Digital Bank, Nova Digital Bank (VEON/Banglalink + Square Group), and Boost Digital Bank (Axiata/Robi).
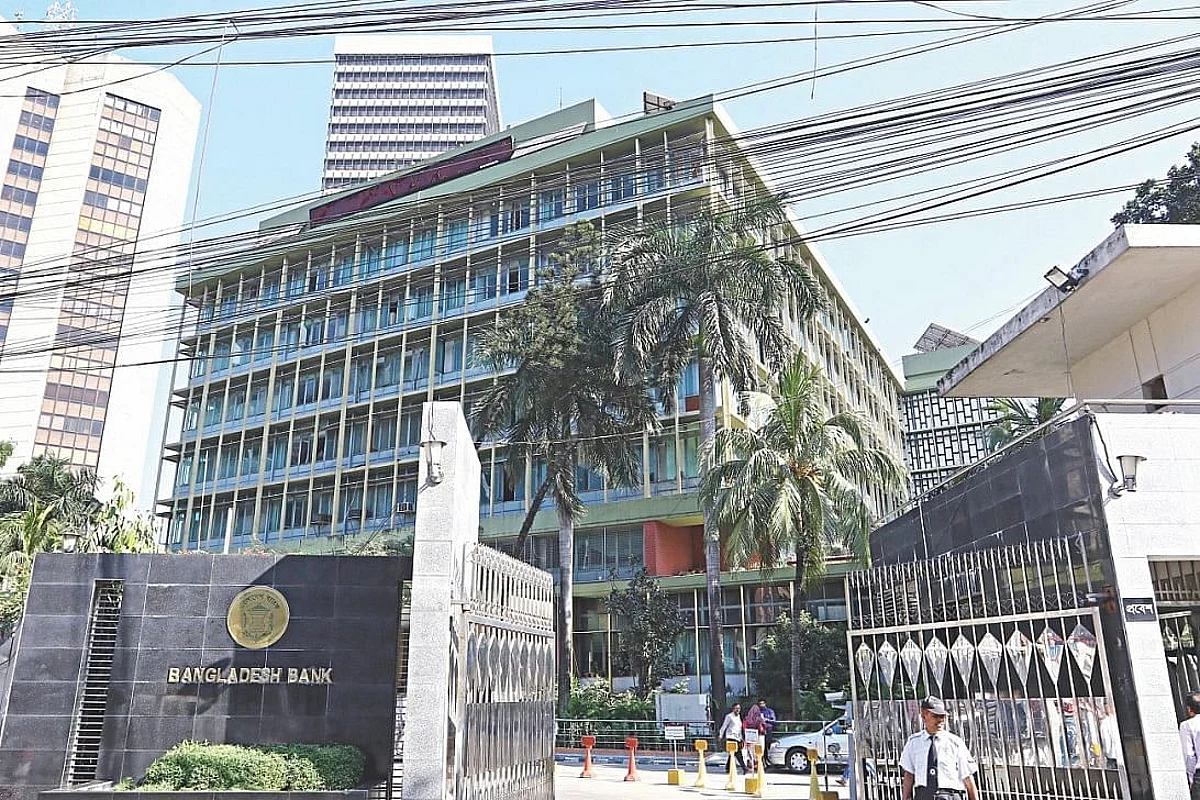
Dhaka, September 24, 2026 — The Bangladesh Bank board has agreed to grant initial approval for the establishment of four digital banks in the country. The central bank will now issue letters of intent (LoIs) to the banks. They will be able to begin operations after completing the remaining formalities.
🏦 The decision was taken at a meeting of the Bangladesh Bank board today, chaired by Governor Mostaqur Rahman. The approval marks a major milestone in Bangladesh's banking sector evolution — bringing digital-only banks closer to reality after more than a year of regulatory preparation.
💼 The Four Approved Digital Banks
The four banks receiving initial approval are:
- 🇧🇹 Digital Banking of Bhutan — sponsored by Bhutan's DK Bank. This is a notable cross-border entry, with a Bhutanese parent company expanding into Bangladesh's banking sector.
- 📱 bKash Digital Bank — sponsored by the shareholders of bKash, Bangladesh's largest mobile financial services (MFS) provider with over 70 million registered users.
- 📱 Nova Digital Bank — sponsored by VEON, the parent company of Banglalink, and Square Group, one of Bangladesh's largest conglomerates.
- 📱 Boost Digital Bank — sponsored by Axiata Limited, the parent company of Robi, Bangladesh's second-largest mobile operator.
The board also decided to issue a letter of intent (LoI) to Kori Digital Bank, which had already received initial approval during the interim government's tenure.
📜 Background: The Application Process
Earlier, during the interim government's tenure, Bangladesh Bank invited applications to establish digital banks. Thirteen entities applied at the time. Their ownership structures included:
- 🏭 Leading industrial groups
- 💰 Microfinance institutions
- 📱 Mobile operators
- 📱 Mobile financial services (MFS) providers
Bangladesh Bank accepted applications for digital bank licences from 1 September to 2 November 2025. However, amid various issues, including protests by Bangladesh Bank officials, the approvals were not granted during the interim government's tenure.
🏛 The Political Transition
Ahsan H Mansur was then the central bank governor. After the BNP formed the government, Mansur was removed and Mostaqur Rahman was appointed governor.
No fresh applications were invited afterwards. Instead, the Bangladesh Bank board has agreed to allow four entities from among the earlier applicants to proceed with establishing digital banks — selecting from the 13 original applications based on the strength of their proposals.
💼 What Is A Digital Bank?
Digital banks are banks that operate entirely online without physical branches. They offer traditional banking services — deposits, loans, transfers, payments — through mobile apps and web platforms. Globally, digital banks have disrupted traditional banking by offering:
- 💻 Lower operating costs — no branch network overhead.
- 💻 Higher deposit rates — passed on to customers from cost savings.
- 💻 Lower lending rates — through more efficient credit assessment.
- 💻 24/7 service availability — through mobile apps.
- 💻 Greater financial inclusion — reaching unbanked populations in remote areas.
For Bangladesh, where approximately 70 per cent of adults now have access to mobile phones and the MFS ecosystem has reached over 100 million users, digital banks represent a natural next step in financial sector evolution.
📱 Why Telecom-MFS Combinations Are Strategic
Three of the four approved digital banks have telecom or MFS sponsors — bKash, Banglalink (VEON), and Robi (Axiata). This is strategically significant because:
- 📱 Existing customer base — telecom operators have millions of existing customers who can be cross-sold banking services.
- 📱 Distribution network — MFS providers like bKash have extensive agent networks that can support cash-in/cash-out services for digital banks.
- 📱 Data analytics capability — telecom operators have rich customer data that can support credit assessment and product design.
- 📱 Digital infrastructure — existing app ecosystems, payment gateways, and customer service platforms.
The combination of telecom infrastructure with banking licences is expected to accelerate financial inclusion — particularly in rural areas where traditional bank branches are sparse.
📊 Bangladesh's Banking Sector Context
Bangladesh's banking sector currently comprises:
- 🏦 61 scheduled banks — including 6 state-owned commercial banks, 3 state-owned specialised banks, 42 private commercial banks, and 10 foreign banks.
- 🏦 35 non-bank financial institutions (NBFIs)
- 🏦 ~11,000 bank branches across the country
- 🏦 Over 100 million MFS users
The addition of four digital banks will not significantly increase the total number of banking entities, but it will introduce a new competitive dynamic — particularly in retail banking, where traditional banks have been slow to digitise.
💼 Implications For Traditional Banks
The entry of digital banks — particularly those backed by bKash, Robi, and Banglalink — is expected to intensify competition in several areas:
- 💰 Retail deposits — digital banks are likely to offer higher deposit rates to attract customers.
- 💰 Small-ticket lending — using alternative data for credit assessment.
- 💰 Payment services — integrating with MFS and card networks.
- 💰 Remittance services — leveraging digital channels for inward remittance distribution.
- 💰 Microfinance-adjacent services — reaching underserved customer segments.
Traditional banks will need to accelerate their own digital transformation to remain competitive — particularly in retail banking, where customer experience has often lagged behind digital-native alternatives.
🏛 Regulatory Framework
Bangladesh Bank has been developing the regulatory framework for digital banks over the past year. Key elements of the framework include:
- 📜 Minimum capital requirements — digital banks are required to maintain minimum paid-up capital similar to traditional banks.
- 📜 Capital adequacy ratio — digital banks must maintain the same CAR as traditional banks.
- 📜 Liquidity requirements — including liquidity coverage ratio (LCR) and net stable funding ratio (NSFR).
- 📜 Cybersecurity standards — enhanced requirements given the digital-only nature of operations.
- 📜 Customer protection — specific rules for digital onboarding, complaint handling, and dispute resolution.
The four approved digital banks will need to comply with these requirements before commencing operations.
📜 What Happens Next?
After receiving the letters of intent (LoIs), the four digital banks will need to:
- 📝 Complete remaining formalities — including final capital arrangements and corporate governance structures.
- 📝 Obtain final banking licences — from Bangladesh Bank after satisfying all regulatory requirements.
- 📝 Build technology infrastructure — including mobile apps, core banking systems, and cybersecurity frameworks.
- 📝 Hire and train staff — particularly in technology, risk management, and compliance functions.
- 📝 Launch customer acquisition — through digital marketing and partnerships with their telecom/MFS parent companies.
Industry observers expect the four digital banks to commence operations within the next 6-12 months, with some launching as early as Q1 2027.
🌏 International Context
Bangladesh's entry into digital banking comes relatively late compared to regional peers:
- 🇵🇭 Philippines — has multiple digital banks including Maya Bank, GoTyme, and UnionDigital.
- 🇵🇰 Pakistan — has launched several digital banks including Mobilink Microfinance Bank and Nayapay.
- 🇮🇳 India — has digital banks and payment banks including Paytm Payments Bank, Airtel Payments Bank, and India Post Payments Bank.
- 🇹🇭 Thailand — has Lightnet and other digital banking initiatives.
Bangladesh's digital banking initiative draws on lessons from these international experiences — particularly the importance of strong cybersecurity, customer protection, and sustainable business models.
💼 Wider Economic Implications
For Bangladesh's broader economy, the entry of digital banks has the potential to:
- 💰 Deepen financial inclusion — reaching underserved rural populations.
- 💰 Reduce the cost of financial services — through digital efficiency.
- 💰 Support SME lending — using alternative data for credit assessment.
- 💰 Improve remittance distribution — particularly for the US$8 billion annual remittance inflow.
- 💰 Stimulate fintech ecosystem — creating opportunities for technology vendors and startups.
The approval of these four digital banks is therefore a significant development for Bangladesh's financial sector — and one that will be closely watched by traditional banks, fintech players, and the broader investment community in the coming months.
This news was originally published by Prothom Alo English. For the full original report, please visit: https://en.prothomalo.com/business/dve117vn1a
📬 Get Bangladesh Trade News in your inbox
Weekly digest of export industry news, policy updates, and market analysis.
📰 Related Stories
✍️ More from System Administrator