Bangladesh Bank Lets Hotels, Retailers Retain 15 Percent of Forex Earnings
Merchants serving foreign visitors can keep up to 15 percent of card receipts in foreign currency accounts to meet their own import needs
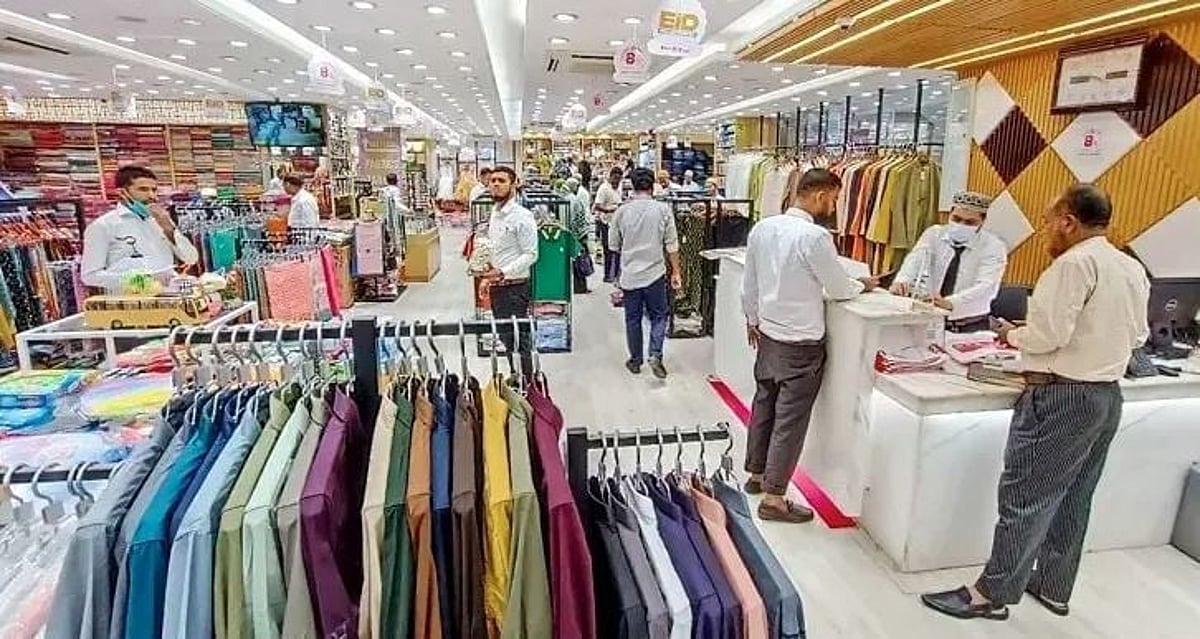
💱 The central bank has introduced a new facility allowing hotels, resorts, restaurants, shopping malls, retail outlets and other businesses to retain a portion of their foreign currency earnings from sales to foreign visitors made through internationally issued cards and other admissible payment instruments. Under a Bangladesh Bank (BB) notification issued on Sunday, Authorised Dealer (AD) banks may allow the merchants concerned to retain up to 15 percent of foreign currency receipts realised through acquiring services in Foreign Currency (FC) accounts maintained in their names — with the remaining 85 percent to be converted into the local currency, Bangladesh Taka.
🗳 The facility's declared purpose is two-fold: to encourage the sale of goods and services to foreign visitors by facilitating international payments, and to give businesses access to foreign currency for their legitimate foreign exchange requirements. Foreign currency retained in these accounts may be used to settle legitimate foreign exchange obligations arising from current account transactions — including payments through international cards — in accordance with applicable foreign exchange regulations, the notification said. It also requires AD banks to ensure that merchants have appropriate arrangements for accepting payments through internationally issued cards and other admissible payment instruments before extending the facility.
📋 What the policy change actually fixes
🏨 The economics of the previous arrangement explain why the change matters. A hotel or resort that earns dollars from foreign guests — paying by international cards through the bank acquiring network — previously saw those receipts converted entirely into taka the moment they settled. Yet the same hotel's cost structure is partly dollar-denominated: imported fixtures and amenities, foreign software subscriptions, overseas marketing and franchise fees, and the commissions of international booking platforms all demand hard currency. Forcing 100 percent conversion obliged merchants to re-purchase the very dollars they had just earned, paying the spread twice and adding to demand in the interbank market.
💸 Allowing a 15 percent retention aligns the plumbing with reality: the merchant keeps a working slice of natural forex income to meet natural forex expenses, which is textbook treatment for economies trying to develop their services exports. The remaining 85 percent still flows to the official market, so the reserve-building function of visitor spending is preserved — the facility is a retention allowance, not an offshore carve-out.
🌏 The tourism and services angle
🛒 For the tourism sector specifically, the facility addresses a chronic friction in Bangladesh's visitor economy. Hotels and resorts have long argued that their inability to hold earnings in the currency their international suppliers and platforms demand raised operating costs and discouraged the investment in card-acceptance infrastructure that foreign guests expect. The notification's requirement that merchants have proper card-acceptance arrangements effectively ties the benefit to exactly that capability — rewarding businesses that make it easy for foreign visitors to spend.
📊 The macro context makes the timing sensible. Bangladesh's inbound spending by foreign visitors remains a fraction of what comparable regional destinations earn — the same central bank card data showing Bangladeshis spending roughly four times abroad what visitors spend here — and every percentage point of visitor-spend growth narrows the services-account gap. Policies that lower the cost of serving foreign customers compound over time: better payment acceptance, easier forex handling and more competitive hospitality pricing together make the difference between a transit stop and a destination.
🛡 On the regulatory-prudence side, the guardrails are sensibly drawn: the retention share is capped, use is restricted to current-account obligations under existing foreign exchange regulation, and AD banks carry the compliance responsibility — meaning the central bank keeps its oversight channel while relaxing a genuine business constraint. It is the kind of liberalisation that increases the attractiveness of doing business without weakening the external account.
🔭 The practical test now falls on implementation: AD banks' willingness to open and operate merchant FC accounts smoothly, the card-acquiring industry's speed in upgrading merchant arrangements, and tourism businesses' discipline in using the facility only for genuine current-account needs. If those pieces work, a modest 15 percent retention will read, a year from now, as an early marker of Bangladesh taking its visitor economy seriously — one notification at a time.
📦 The mechanics also carry a quiet message to the card-acquiring industry. By conditioning the facility on appropriate acceptance arrangements for internationally issued cards, Bangladesh Bank is effectively telling acquiring banks and payment processors to invest in merchant onboarding — the terminals, the QR acceptance, the settlement wiring — because their merchant clients now have a direct financial reason to want them. Acquirers gain a differentiated service to sell; merchants gain a reason to upgrade; and the central bank gets the card-acceptance expansion it has sought through campaigns for years, achieved here through incentive rather than instruction. It is a small masterclass in aligning commercial self-interest with a policy objective.
📋 Precedent also suggests the facility may be a first step rather than a final one. Central banks in comparable economies have typically begun with conservative retention shares for services earnings and later extended them — to higher caps, to more sectors, or to exporters of IT and business-process services whose foreign receipts resemble tourism's natural-hedging profile. Bangladesh's software and freelancing exporters have long made precisely this case: their earnings arrive in dollars, their expenses — cloud services, software licences, marketing — are dollar-denominated, and forced full conversion adds avoidable cost to one of the country's most promising services sectors. If the merchant-retention facility functions smoothly, expect those sectors to petition for the same treatment with this notification as their template.
This news was originally published by The Financial Express. For the full original report, please visit: https://thefinancialexpress.com.bd/trade/hotels-resorts-shops-allowed-to-retain-15pc-of-forex
📬 Get Bangladesh Trade News in your inbox
Weekly digest of export industry news, policy updates, and market analysis.
📰 Related Stories