Women's Participation In Bangladesh Agent Banking Grows: BB Report
Female-owned agents rise 23.8% to 1,775, women hold 48.6% of deposit accounts, but ownership still far below BB's 50% target at 11.5%
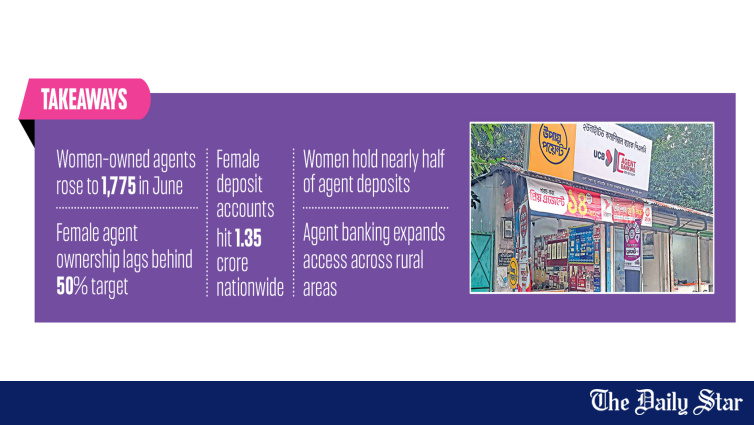
👥 Women are playing a growing role in Bangladesh's agent banking system, with female-owned agents and accounts continuing to increase, particularly in rural areas. Women now own 11.5 percent of all agents and hold 48.6 percent of deposit accounts through the channel, according to a Bangladesh Bank (BB) report. The growth represents meaningful progress in financial inclusion for women, though significant gaps remain relative to the central bank's targets.
📊 The number of women-owned agents rose 23.8 percent year-on-year to 1,775 in June 2026, up from 1,434 a year earlier. Women-owned agents grew faster in rural areas, rising 26.1 percent, compared with 14 percent in urban areas. "This shows a positive trend towards greater financial inclusion for women, especially in rural areas, while urban areas are quickly catching up," BB said in its Agent Banking Statistics report for April-June 2026.
💰> Growth Across Account Types
- 👥 Women-owned agents: 1,775 (up 23.8% YoY)
- 👥 Female agent share: 11.5% (up from 10.3% in March)
- 💰 Women's deposit accounts: 48.6% of total (up 12.8% YoY)
- 💰 Women's loan accounts: Up 6.1% YoY
- 📊 Rural female agent growth: 26.1%
- 📊 Urban female agent growth: 14.0%
- 📊 BB target: 50% women-owned agents
- 📊 Current vs target: 11.5% vs 50% (gap: 38.5pp)
- 🏛 Banks providing agent banking: 30 scheduled banks
- 👥 People per agent outlet: 8,487 (vs 15,132 per bank branch)
📜 Rural Growth Outpaces Urban
Women-owned deposit accounts increased 12.8 percent year-on-year in June, with growth stronger in urban areas than in rural areas. Women's loan accounts also increased, rising 6.1 percent year-on-year, with growth slightly stronger in urban areas than in rural areas. "Overall, the data reflects growing financial opportunities for women in both urban and rural areas, with particularly strong progress in rural participation," the central bank added. The rural-urban growth pattern is notable — female agent ownership grew faster in rural areas (26.1% vs 14.0%), while female deposit and loan account growth was stronger in urban areas. This suggests that women in rural areas are increasingly becoming agent banking providers, while urban women are increasingly using agent banking services.
⚠ Gap To 50% Target: 38.5 Percentage Points
Despite the growth, women's ownership of agents remains well below the target set by BB in a Banking Regulation and Policy Department circular letter dated May 8, 2025. The circular requires women to own 50 percent of all agents. As of June 2026, women-owned agents accounted for only 11.5 percent of the total, although the share had increased from 10.3 percent in March. The 38.5 percentage point gap between the current 11.5% and the BB's 50% target illustrates the magnitude of the challenge. At the current growth rate (approximately 1.2 percentage points per quarter), reaching the 50% target would take over 30 quarters — nearly 8 years.
🏛 Agent Banking As Financial Inclusion Channel
In June 2026, 30 scheduled banks were providing agent banking services through thousands of outlets across the country, most of them in rural areas. Agent banking has become an important channel for financial inclusion, helping banks reach underserved and unbanked people, particularly in rural areas, BB said. In June 2026, each agent banking outlet served an average of 8,487 people nationwide, compared with 15,132 per traditional bank branch. The lower people-per-outlet ratio for agent banking (8,487 vs 15,132) demonstrates that agent banking outlets provide more granular geographic coverage than traditional bank branches — each agent serves a smaller population, meaning more people have a financial access point within reasonable distance.
🌏> Strategic Context: Women's Financial Inclusion
For Bangladesh's broader financial inclusion agenda, the agent banking data carries strategic significance. Women's financial inclusion — access to savings accounts, credit facilities, insurance and payment services — is not merely a social equity issue but an economic growth imperative. Research by the World Bank and IMF consistently shows that increasing women's financial inclusion correlates with higher household savings, improved child welfare outcomes and greater female labour force participation.
The BB's 50% women-owned agent target, while ambitious given the current 11.5% baseline, reflects the strategic importance of female agents for reaching women customers. Cultural norms in many parts of Bangladesh mean that women are more comfortable conducting financial transactions with female agents — making female agent ownership a critical lever for expanding financial inclusion among the female population.
"The success of agent banking depends on effective regulation, strong agent management and continued efforts to address challenges such as digital literacy and agent sustainability," the report said. The reference to digital literacy and agent sustainability highlights the structural challenges that need to be addressed to sustain the growth trajectory — without investment in digital skills training and agent business model viability, the current growth rates may not be sustained.
The coming years will reveal whether the current growth momentum can be accelerated to close the gap to the 50% target — or whether the 38.5 percentage point gap proves structurally difficult to bridge within the timeframe the central bank has envisioned. For Bangladesh's women, the agent banking channel represents one of the most accessible pathways to formal financial services — and the growth in female ownership of agents is a positive signal that the channel is increasingly serving the population it was designed to reach.
This news was originally published by The Daily Star. For the full original report, please visit: https://www.thedailystar.net/business/economy/news/womens-participation-agent-banking-grows-4275826
Related on BangladeshExport
📬 Get Bangladesh Trade News in your inbox
Weekly digest of export industry news, policy updates, and market analysis.
📰 Related Stories