Non-Performing Loans Below 5% In 13 Bangladesh Banks: Ranking Reveals Governance Gap
While national NPL ratio hits 32.78% with Tk 606,555 crore in defaults, 13 private banks maintain below 5% through disciplined lending, independent approval processes and SME/consumer focus
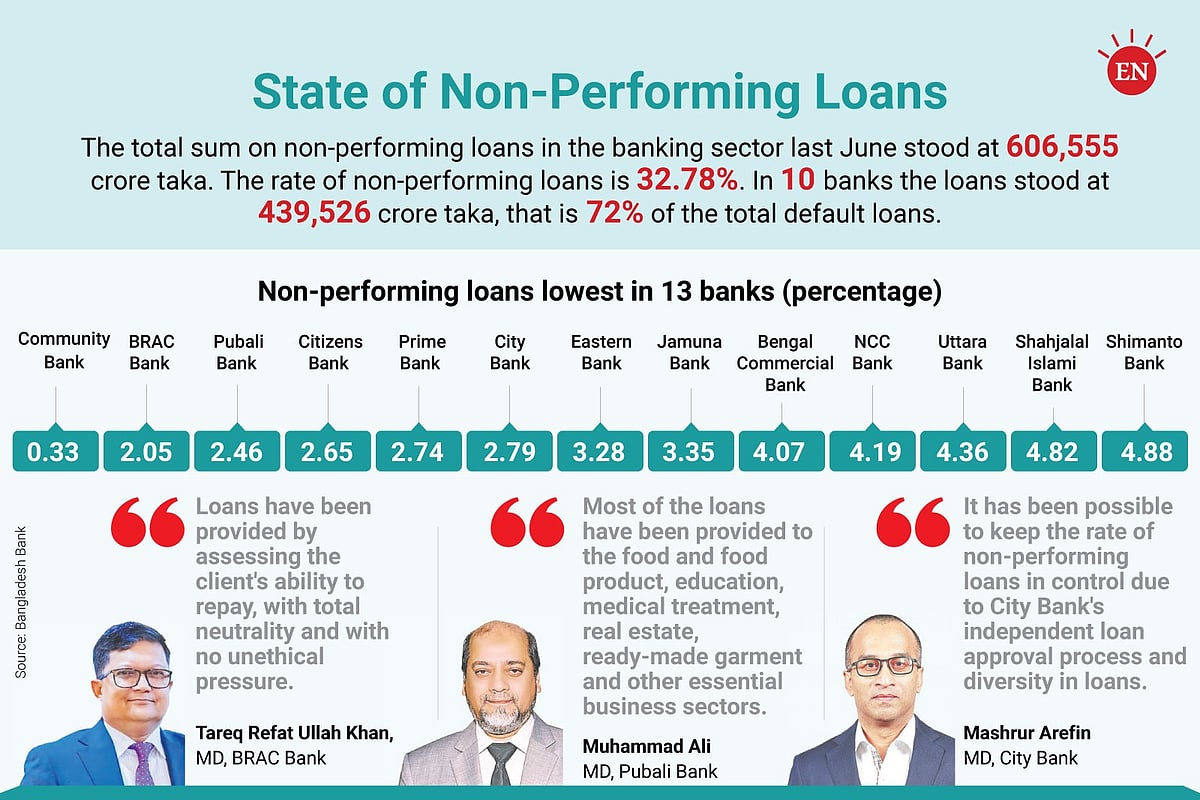
📊 Nearly Tk 33 out of every Tk 100 in loans disbursed by the country's banking sector are now classified as non-performing, meaning that 33 per cent of loans are in default. By the end of June, non-performing loans in Bangladesh's banking sector reached Tk 606,555 crore — the highest in the world as a percentage of total outstanding loans. Yet amid this crisis, 13 private-sector banks have managed to keep their NPL ratios below 5 per cent through disciplined lending, independent loan approval processes and diversified portfolios.
🏛 Senior officials of these banks say that disciplined and independent loan approval processes, careful assessment of borrowers' repayment capacity, and a focus not only on large corporate loans but also on small and medium-sized enterprises (SMEs) and consumer lending have helped keep NPLs under control. According to the central bank's latest data as of June, all 13 banks with NPL ratios below 5 per cent are from the private sector. The group includes both newer-generation banks and first-generation banks.
💰 The 13 Banks: NPL Ranking
- 📊 #1 Community Bank: 0.31% (Tk 5cr NPL out of Tk 1,633cr total)
- 📊 #2 BRAC Bank: 2.05% (Tk 1,548cr NPL out of Tk 75,621cr)
- 📊 #3 Pubali Bank: 2.46% (Tk 1,789cr NPL out of Tk 72,576cr)
- 📊 #4 Citizens Bank: 2.65%
- 📊 #5 Prime Bank: 2.74% (Tk 948cr NPL)
- 📊 #6 City Bank: 2.79% (Tk 1,514cr NPL)
- 📊 #7 Eastern Bank: 3.28% (Tk 1,520cr NPL)
- 📊 #8 Jamuna Bank: 3.35%
- 📊 #9 Bengal Commercial Bank: 4.07%
- 📊 #10 NCC Bank: 4.19%
- 📊 #11 Uttara Bank: 4.36%
- 📊 #12 Shahjalal Islami Bank: 4.82%
- 📊 #13 Shimanto Bank: 4.88%
📜 Governance: The Key Differentiator
Tareq Refat Ullah Khan, Managing Director of BRAC Bank, said: "In credit risk management and loan approval, good governance and proper risk assessment are the main tasks. This is the key to maintaining the quality of BRAC Bank's loans. Loans have been extended by assessing borrowers' repayment capacity in a completely neutral manner without any unethical pressure."
Pubali Bank Managing Director Mohammad Ali said: "No loan at this bank has been granted based on the sole advice or personal recommendation of me or any senior official. Loans are approved through a fully institutional and systematic assessment process. The borrower's personal or political identity is also not taken into consideration when granting loans." He further said: "Most of the bank's large loans have been provided to essential business sectors such as food and food products, education, healthcare, housing, and garments. As a result, a relatively small proportion of our loans have become non-performing."
City Bank Managing Director Masrur Arefin said: "City Bank's independent loan approval process and diversified lending portfolio have enabled us to keep the NPL ratio under control. SME and consumer lending are providing us with significant comfort. Banks that are placing greater emphasis on SME and consumer lending are performing well." The consistent theme across all three CEOs — independent loan approval, institutional assessment processes, and diversification into SME/consumer lending — identifies the governance practices that separate healthy banks from distressed ones.
⚠ The Contrast: Worst Performers
According to Bangladesh Bank data, the total amount of non-performing loans in the country's banking sector stood at Tk 606,555 crore last June, representing 32.78 per cent of total outstanding loans. Of this amount, Tk 439,526 crore in NPLs was concentrated in 10 banks, accounting for 72 per cent of the total non-performing loans.
The merged banks have the highest NPL ratios. Among them, 97.08 per cent of First Security Islami Bank's loans, 96.78 per cent of Union Bank's loans, 78.15 per cent of Social Islami Bank's loans, and 70.81 per cent of EXIM Bank's loans are currently classified as non-performing. At National Bank, 65.74 per cent of loans are classified as non-performing, compared with 63.38 per cent at IFIC Bank and 56.40 per cent at AB Bank. In addition, 43.98 per cent of the loans at state-owned Agrani Bank are now classified as non-performing.
🌏 Strategic Context: Governance As Competitive Advantage
The 13-bank ranking provides compelling evidence that Bangladesh's banking sector crisis is not uniform — it is concentrated in banks where governance failed. The banks that maintained below 5% NPL ratios did so through the same basic principles that banking supervision globally promotes: independent credit assessment, institutional (not personal) decision-making, portfolio diversification and risk-based lending. The fact that these practices — widely known and internationally standard — were sufficient to keep NPLs below 5% while peers saw ratios above 50% demonstrates that the crisis is not an inevitable consequence of Bangladesh's economic environment but a direct result of governance choices.
For depositors, the ranking provides a practical guide: banks with low NPL ratios are also seeing higher deposit growth, as customers shift their savings toward institutions with demonstrated asset quality. The market mechanism — depositors voting with their savings — is creating a natural differentiation between well-governed and poorly governed banks. If Bangladesh Bank's new KPI framework for bank CEOs can extend these governance practices across the sector, the NPL crisis could begin to stabilise from the bottom up.
This news was originally published by Prothom Alo English. For the full original report, please visit: https://en.prothomalo.com/business/gt6finp6du
Related on BangladeshExport
📬 Get Bangladesh Trade News in your inbox
Weekly digest of export industry news, policy updates, and market analysis.
📰 Related Stories