Dhaka Bank Opens Its 41st Sub-Branch at Katirhat in Chattogram
Additional MD AKM Shahnawaj inaugurates the Katirhat outlet under the Hathazari branch, advancing the Transforming Together vision
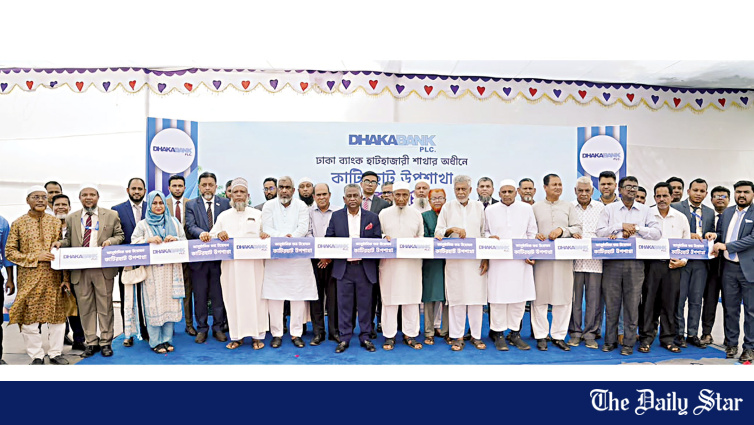
🏦 Dhaka Bank PLC has opened its Katirhat sub-branch under the Hathazari branch in Chattogram — the bank's 41st sub-branch nationwide, according to a press release. AKM Shahnawaj, additional managing director of the bank, inaugurated the new outlet as chief guest, joined by senior regional officials and local community figures including Md Jahangir Alam, senior executive vice-president and regional manager of the Chattogram region; Md Altamas Nirjhar, executive vice-president and head of the general services division; Md Rashedul Alam, vice-president of the Katirhat Madrasa Operating Committee; Shahadat Hossain Chowdhury and Alamgir Zaman, former chairmen of Dhalai Union; and Mahbubul Alam Chowdhury, senior consultant at Apollo Imperial Hospital.
🚀 In line with Dhaka Bank's vision, Transforming Together, the bank is advancing its strategic goal of expanding its branch and sub-branch network across the country, Shahnawaj said at the inauguration. He emphasised that the Dhaka Bank family remains committed to maintaining Excellence in Banking — strengthening customer relationships, expanding innovative banking services and ensuring sustainable growth. The inauguration of the Katirhat sub-branch marks another significant milestone in the bank's continued journey of progress, he added.
🔍 The sub-branch model: banking's low-cost outreach tool
📦 The quiet significance of the announcement lies in the format. Sub-branches — a lighter authorisation category Bangladesh Bank introduced to widen banking access — allow a bank to bring deposit, withdrawal, remittance and basic account services into semi-urban and rural trade centres at a fraction of the cost of a full branch, under the supervision of a parent branch. For a private bank, each sub-branch is effectively a low-risk experiment in local deposit mobilisation: if the catchment responds, the outlet grows; if it does not, the model has cost little to test.
💰 Katirhat is a telling choice of location. The Hathazari belt of Chattogram blends agricultural trade, small manufacturing and remittance income from the district's long tradition of overseas migration — the classic profile of the markets where Bangladesh's retail banking still has genuine growth runway, in contrast to Dhaka's saturated branchscape. Sub-branch expansion into such areas is how private banks capture the deposits that once went to state banks, post offices or the mattress — funding that then feeds the lending book from a cheaper, stickier base.
🎯 For Dhaka Bank specifically, the 41-sub-branch mark keeps pace with the sector-wide push that followed regulatory encouragement: banks that once concentrated on corporate lending in Dhaka and Chattogram now compete for retail relationships because deposits are the scarce asset of the current high-liquidity-preference era. The institution's messaging — transformation, excellence, customer relationships — is standard bank-speak, but the pattern behind it is real: sustained, incremental network growth aimed at the retail depositor.
🌏 The wider picture matters for readers who track the sector rather than any single bank. Each sub-branch opening anywhere in Bangladesh is a small indicator of confidence — in local commerce, in remittance flows, and in the durability of the deposit franchise that funds the whole system. Forty-one of them is a network; the visible, everyday banking they bring to places like Katirhat is how financial inclusion stops being a policy document and starts being a queue at a counter on market day.
📈 The competitive backdrop for this quiet expansion deserves emphasis, because sub-branches have become the sector's preferred growth instrument precisely when full-service branches face harder economics. Rising rents, security costs and the shift of routine transactions to digital channels have made the traditional branch a heavy asset, while Bangladesh Bank's sub-branch guidelines let banks plant a flag in an under-banked trade centre with modest floorspace, a handful of staff and the parent branch's back office doing the heavy lifting. Across the industry, banks that once measured prestige by marble lobbies now measure reach by sub-branch counts — a strategic pivot that Katirhat's inauguration embodies.
🧪 There is also a technology logic embedded in the format. A modern sub-branch pairs a small physical presence with full digital rails: instant account opening, card issuance support, mobile-app onboarding and QR acceptance for local merchants can all be delivered from a compact outlet, making each location both a service point and a digital-adoption hub. For markets like Katirhat — where smartphone penetration grows yearly but hand-holding is still needed to move savers from cash to accounts — the sub-branch is the bridge, and the staff manning it are as much digital educators as tellers.
💵 The employment dimension rounds out the story. Each sub-branch brings a handful of direct jobs — officers, cashiers, security — and a wider orbit of indirect activity: renovated premises, local vendors, and the small businesses that benefit when banking hours and market days coincide. In union-level economies, the arrival of a formal financial institution also tends to raise standards — for wage payments, savings habits and even record-keeping among the shops nearby. None of this shows up in the bank's press release, but it is exactly what the sub-branch policy was designed to produce, and it is why a 41st opening in a Chattogram market town is worth more attention than its ceremony budget suggests.
This news was originally published by The Daily Star. For the full original report, please visit: https://www.thedailystar.net/business/organisation-news/news/dhaka-bank-opens-41st-sub-branch-ctg-4307236
📬 Get Bangladesh Trade News in your inbox
Weekly digest of export industry news, policy updates, and market analysis.
📰 Related Stories



